After a windstorm, hail event, or fallen branch, Connecticut homeowners need two kinds of information: a documented assessment of the roof and clear instructions from their insurer about the policy and reporting process.
Roof damage, repair scope, deductibles, coverage, and reporting deadlines are separate questions. A contractor can describe observed conditions and proposed construction work. Your insurer or agent can explain the policy terms and claim process that apply to your home.
Before deciding how to fund roof repairs, gather the information needed to discuss the damage with your contractor and insurer. A useful starting question is what has changed on the roof, and what documentation is needed? Keep photos, dates, and written repair scopes together.
What Connecticut Homeowners Should Know at a Glance
- Ask your insurer how the policy addresses the reported event, existing roof condition, exclusions, and required documentation.
- Confirm the applicable deductible and coverage terms with your insurer before comparing funding options.
- Keep roof age, prior repairs, maintenance records, and earlier photographs with the current damage documentation.
- Document visible damage safely and contact your insurer or agent for reporting steps and deadlines.
- If the roof is actively leaking, protect the home immediately and start documenting the damage the same day.
| Situation | Roof Findings to Document | Questions to Confirm |
|---|---|---|
| Wind removed shingles after a recent storm | Affected roof slopes, missing shingles, and the date damage was first observed | What repair limits and policy reporting requirements apply? |
| Tree branch hit the roof | Visible impact, roof openings, interior water, and affected components | Who will assess concealed damage and explain the policy process? |
| Leak appeared after heavy weather | Leak location, weather timing, and roof or attic findings | What evidence distinguishes a new event from existing wear? |
| Roof is nearing the end of its life | Roof age, prior condition, repair history, and newly observed damage | How will existing condition and the reported event be evaluated? |
A clear roof assessment should identify visible damage, possible concealed work, access limits, and the repair options. Keep that construction scope separate from the insurer’s coverage decision.
Start With One Basic Question: Is This Sudden Damage or an Old Roof Problem?
A recent storm and an older roof problem can produce similar symptoms. Record the event, prior repairs, existing stains, and newly observed damage so the roof assessment and insurer review have useful context.
That distinction is why homeowners should not jump straight to “insurance will cover this” just because a leak appeared after bad weather. Sometimes the storm caused the failure. Other times the storm simply revealed a weak spot that had already been developing for months or years.
Warning signs that the roof may have already been struggling include:
- curling, brittle, or heavily worn shingles
- older flashing details that have leaked before
- multiple past patch repairs in the same area
- visible granule loss or aging across large roof sections
- stains that predate the most recent storm
If the roof has both storm damage and age-related wear, the next step should be a documented inspection, not guesswork from the driveway.
Compare the Likely Repair Cost to Your Deductible
Read the declarations page and ask your insurer or agent which deductible, coverage terms, settlement provisions, and deadlines apply. A repair estimate alone does not establish coverage or the amount payable under a policy.
A repair estimate should account for the affected roof layers and connected damage. A few missing shingles may be a modest repair. A branch puncture, soaked roof decking, damaged flashing, wet insulation, and interior staining can quickly turn into a much larger project.
Keep the relevant policy information beside the written repair estimate. Ask your insurer or agent to explain any event-specific deductible and any additional information needed to review the loss.
Think Beyond the Immediate Repair Bill
Use the policy conversation to clarify the next steps and records needed for the reported damage. Questions to ask include:
- Which deductible and settlement terms apply to this reported event?
- Is the damage clearly documented and tied to a recent event?
- What notice, inspection, and documentation deadlines apply?
- What should be documented before cleanup or permanent repairs?
The insurer can explain how to report the loss and what information it needs. Keep a written record of the instructions, claim reference when applicable, and any requested documents.
If you are unsure about reporting or deadlines, contact your insurer or agent promptly. Arrange a roof assessment as appropriate without assuming it replaces policy reporting requirements.
Get the Roof Inspected Before You Assume the Scope
A ceiling stain alone does not identify the roof problem. Inspection may reveal a flashing defect, puncture, attic moisture, or a larger damaged area. Document the findings and any limits on what could be observed.
A roof inspection helps answer the questions that actually matter:
- Is the damage recent and event-related?
- How large is the affected area?
- Are there signs of older maintenance problems in the same section?
- Is the roof repairable, or is a larger replacement discussion starting to make sense?
- Are gutters, flashing, vents, fascia, or interior areas also involved?
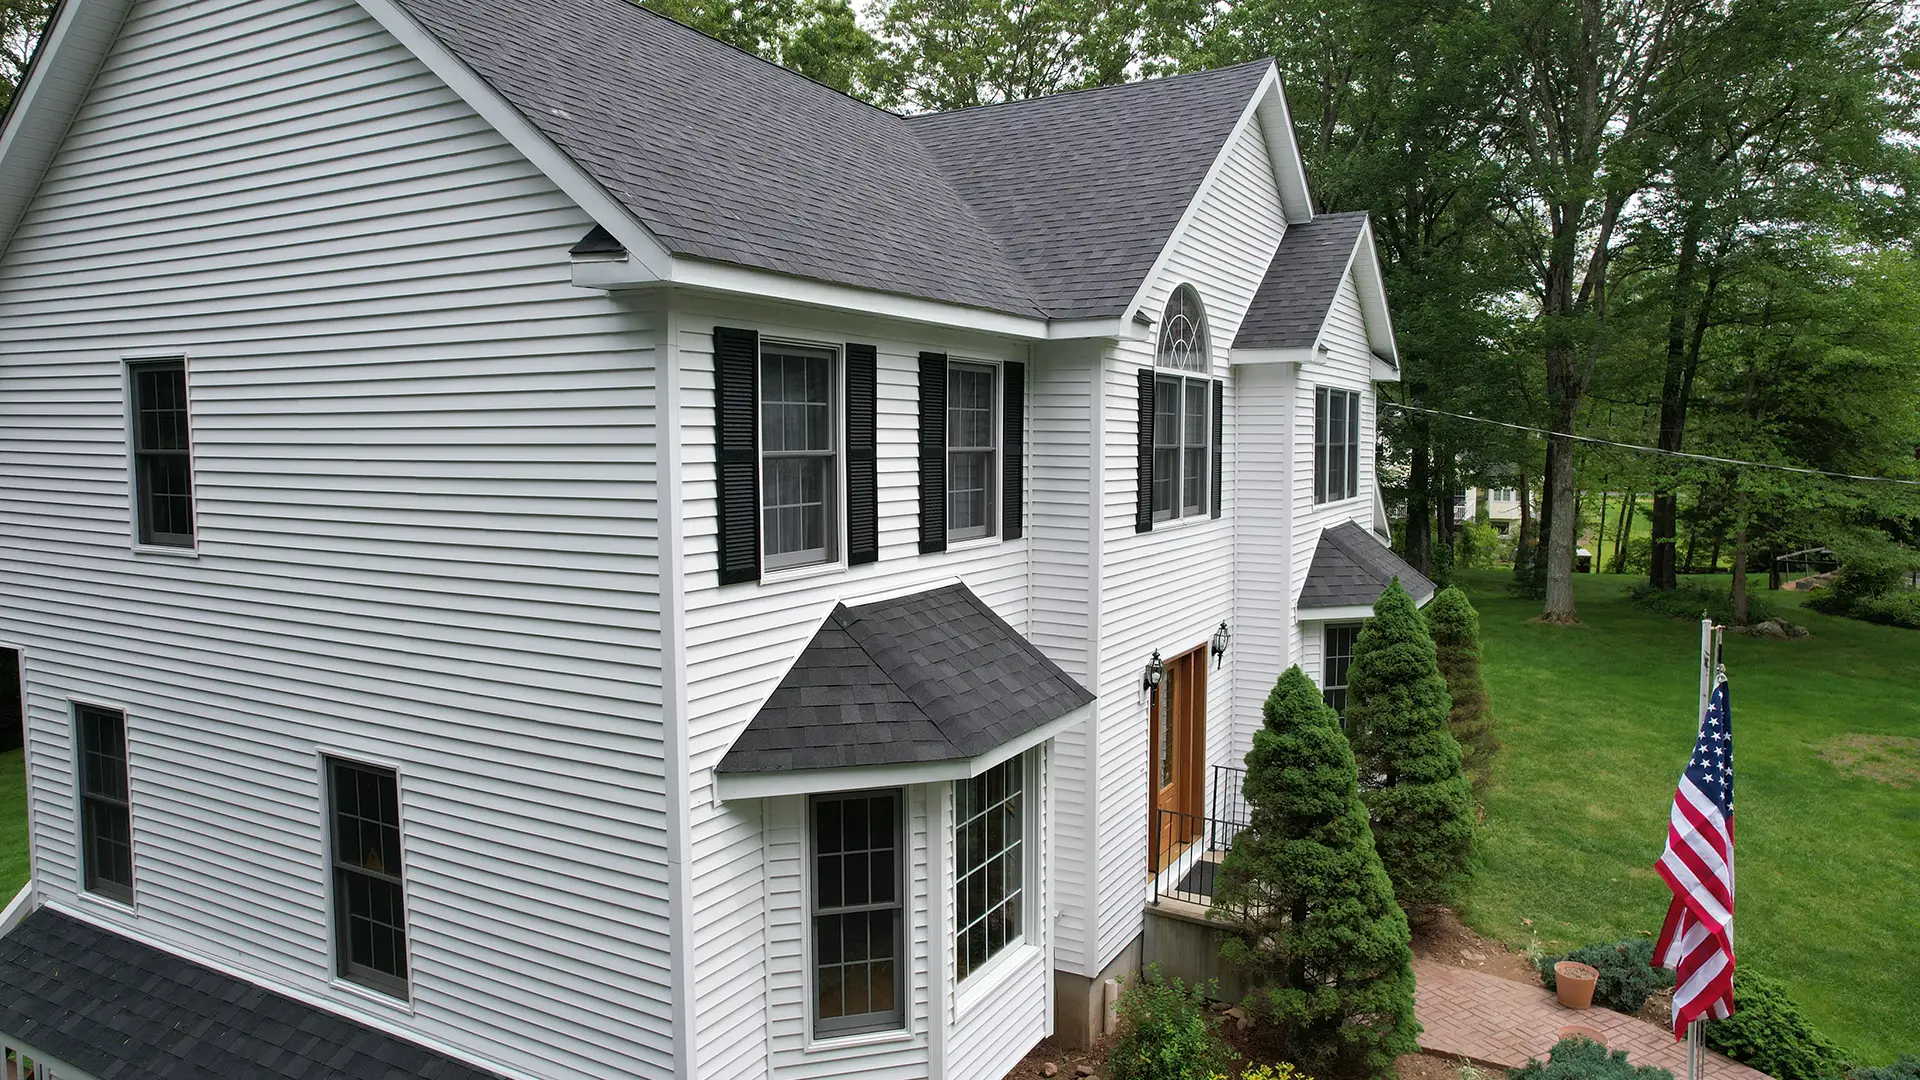
Ellis Builders can assess accessible roof conditions and discuss targeted repair or replacement options. Photographs and a written construction scope can support your conversation with the insurer, which determines coverage.
What to Document Before You File
Document visible damage from safe locations, including what happened, when it was noticed, and the conditions before cleanup or temporary protection. Do not enter an unsafe roof, attic, or room to collect evidence.
- Take wide photos of the house and close photos of visible damage.
- Photograph fallen limbs, dented metal, displaced shingles, interior stains, and any active leaking.
- Write down the date of the storm and the first time you noticed the problem.
- Keep receipts for emergency tarping or water-control measures.
- Save inspection notes and repair estimates in one place.
If the roof is leaking right now, protect the interior first. Insurance carriers generally expect homeowners to take reasonable steps to prevent additional damage after a loss.
If you need an immediate action plan, Ellis already has a detailed emergency roof repair guide for Connecticut homeowners and a broader storm damage roof repair checklist that can help you stay organized.
Common Connecticut Roof-Damage Scenarios
| Scenario | Practical Next Step | Why |
|---|---|---|
| A few shingles blew off, no interior leak, deductible is high | Document the affected area and request a repair scope | Confirm any reporting requirement and applicable deductible with the insurer |
| A branch punctured the roof and water entered the attic | Arrange safe temporary protection and contact the insurer promptly | Impact may affect multiple roof layers and interior materials |
| The roof leaked after heavy rain but is old and worn in several areas | Document the leak and review both new damage and existing wear | The storm may have exposed a broader maintenance or replacement issue |
| Hail appears to have affected multiple slopes and metal accessories | Document visible impacts and arrange a roof assessment | The insurer can explain what inspection and documentation it requires |
| A small flashing leak appeared around a vent or chimney | Request a flashing and surrounding-roof assessment | A written scope should explain the source and repair limits |
The key is not to treat every leak the same way. Connecticut homes take hits from wind, wet snow, tree debris, repeated rain, and changing temperatures. The cause, age, and size of the problem should drive the decision.
Damage to Discuss With Your Insurer
Ask your insurer about reporting requirements when you observe conditions such as:
- storm-created openings or punctures
- widespread wind damage across multiple sections
- hail damage affecting shingles, vents, flashing, or gutters
- interior water damage connected to a documented exterior event
- tree impact or debris damage that affected the roof system structurally
The construction review should include connected materials: underlayment, decking, flashing, gutters, attic components, and interior damage where water entered.
Repair Scopes to Compare
A written repair scope can help you understand the work involved while discussing policy questions with your insurer. Examples to review with the contractor include:
- isolated shingle replacement
- minor flashing corrections
- small leak repairs tied to aging materials
- damage costs that land near or below the deductible
- repairs on a roof that is already at the end of its service life
That is also where it helps to compare today’s repair against the bigger picture. If the roof is aging out, you may be better served by reviewing the Connecticut roof replacement cost guide and deciding whether a short-term patch is still worth it.
How Ellis Builders Helps Document Roof Conditions
Ellis Builders helps Connecticut homeowners assess storm-related roof conditions, document accessible damage, and compare repair and replacement scopes. The review can also identify existing wear and areas that require further investigation.
The goal is to explain the observed roof condition, proposed work, and remaining uncertainties so you can discuss construction details with the contractor and policy questions with your insurer.
If you want a direct next step, start with the contact page. If you want service context first, you can also review the main roofing services page or the Connecticut service areas page.
Serving Homeowners Across Connecticut
Ellis Builders works with homeowners across Connecticut who need a clear, practical roof assessment after wind, hail, branch impact, or sudden leaking. For policy and reporting questions, contact your insurer or agent. A documented roof inspection can help clarify the construction scope. You can also start from the Southbury roofing page, browse wider service areas, or use the contact page to request help.
Frequently Asked Questions
Should I call a roofer or my insurance company first?
Protect people first, arrange safe temporary protection where needed, and document visible damage. Contact your insurer or agent promptly for reporting steps and deadlines, and arrange a contractor assessment of the roof conditions.
Will homeowners insurance cover an old leaking roof?
Coverage depends on the policy, reported event, existing condition, and the insurer’s review. Ask your insurer or agent how the policy applies to the observed leak and roof condition.
What if the repair cost is close to my deductible?
Request a written repair estimate and ask your insurer or agent to explain the applicable deductible, policy terms, and reporting requirements before comparing funding options.
Can storm damage affect more than just shingles?
Yes. Flashing, roof decking, vents, gutters, attic materials, and interior ceilings can all be part of the real scope.
Who can help me inspect roof damage in Connecticut?
Ellis Builders can help Connecticut homeowners evaluate accessible roof damage, document findings, and compare repair and replacement options. Your insurer determines coverage under the policy. Call (860) 499-4970 or use the contact page.